Sunday, August 4, 2019

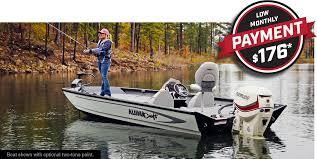
It's All About The Payment

By Myril Shaw, Dealer Profit Services


image

Let’s think about this for a minute…when was the last time you saw or heard a car ad, whether on the web, on TV, in print or on the radio that said something special like, “Come on in get your new Nisan Altima for the low, low price of $24,739.00”? 
 That was a trick question. The answer is “Never”! 
 What you did hear or see was something along the lines of, “For a limited time, get your new Nissan Altima for a low payment of only $199.00 per month." 
 The car guys are not dumb…notwithstanding your opinion or your experience. They sell 1,500 or 2,500 cars for a reason (or several reasons). One of those reasons is that they know how to connect with what the buyers are concerned about. 
 One the biggest concerns is not, "How much does this cost?”, or even if that is the underlying concern the easiest way to diffuse that issue, and attract the buyer is to flip the concern on its side by answering the base concern, “Can I afford this?" 
 "Can I afford this?" 
 Most buyers (truth be told, 90% of all buyers) do not have liquid cash sitting around to enable them to see a $25,000 $50,000 or $100,000 unit and just write a check with no other action. One way or another, directly or indirectly, your buyers will be making payments once they buy your unit. Maybe they will be working to replenish equities that they sold. Perhaps they will need to refill their home equity line. Perhaps they are just making payments to someone who does not benefit you, except that you have sold a unit. 
 Make a big purchase and payments are going to happen somewhere. 
 Why don’t you ensure that you are the beneficiary of those payments by having them go to a lender you have a relationship with and from whom you receive reserve and through whom you can also sell protective products? 
 So…lead with payment 100% of the time. From the first contact on the web or in other advertising through unit hanger signs to a qualifying question in sales, "What payment are you looking for?”, payment is the pitch. 
 There are online tools available that allow you to couple a web-based, soft credit pull, “Get Pre-qualified” lead with the next logical step – “Shop By Payment”. These tools let the buyer suggest their payment preference and then match that to your inventory – and yes, they still work with customers who have unrealistic expectations. 
 There are some common misconceptions about posting or suggesting the payment. Most common among these is that if you show a payment, somewhere in close proximity you have to show the price and all the terms allowing you to arrive at that payment. False! 
 You do need to show the small print, “Based on qualifying credit.” Beyond that, you must follow a consistent set of rules for the terms you are using and be able to demonstrate that you follow those rules all the time. 
 For example, for units less than $25,000 the APR used is 7.9% and the term is 120 months; for units $25,000 - $50,000 the APR is 7.25% and the term is 144 months; for units $50,000 - $100,000 the APR is 6.9% and the term is 180 months; and, for units over $100,000 the APR is 6.24% and the term is 240 months. Obviously, this is just an example and these actual numbers will change as the market conditions change, but the principle is correct. You simply need to be able to pull out a term sheet that you can show to every customer and say, “This is how we came up with that payment." 
 The guideline for setting your APR is to take mid-prime customer, look at the average Buy Rate from your lenders and set the rate so that you can get at least 6% reserve. Do the same thing for setting the term. Based on this guideline, super-prime customers can do better, non-prime customers will not be surprised, and you still have some room to negotiate if needed. 
 Everyone in the store needs to know the rules – and if asked, honest answers must always be given. There is no reason to ever lead with, or discuss, anything except the payment derived from your rules. 
 By leading with payment early and often you accomplish two things. First, you send the clear message that you can handle the buyer’s financing needs. Second, you hook the buyer by letting them know that, "Yes”, they can afford it.  
The final benefit of the payment approach is that it sets the stage for selling the Optional Protective Products. These are always sold by payment first and now the expectation is set! 
 Payment, payment, payment! 
 Attract, retain and close buyers by focusing on payment. 
 Long live payment!

Dealer Profit Services, LLC can help. Whether you want someone to take over your F&I and just drive profit to your store, help you some of the time, need some quick advice or just provide F&I Training/Consulting, we are here to help you. Contact us anytime at info@dealerprofit.com or give us a call at (470) 326-0966. 

Sunday, July 21, 2019

7 Tips For Maximizing F&I Profit


by Myril Shaw, Dealer Profit Services


image

Are your F&I results everything you would like them to be? There are always ways to improve your results. Here are seven tips which can help you drive your results to the levels that you would like. 
 1) Advertise your Finance capabilities and make your website sticky. Make sure every customer-facing message, from print-ads and in-store signage through to and especially your website advertises your financing capabilities. You would be surprised at the number of potential buyers who are unaware that you can be a “one-stop shop.” Your mission is to make them aware that you have “competitive financing available” early and often. Get them the message before they go to their local bank or credit union, before they draw down their home-equity line or sell stocks or bands. Remember that 90% of cash buyers are using liquid cash. 
 Make sure that you are using soft credit pull technology on your website to have the “Get Pre-qualified.” This technology allows for a full bureau pull based strictly on their name address and phone number and has no effect on their credit score. They can print a certificate that says, “Congratulations! You are pre-qualified…” with your store named. Now you have solid lead to call and set an appointment with. It also makes your website more interesting and sticky. 


image

Use attractive and engaging inventory photos on your site. Use 360-degree photography inside and outside your unit. Your customers will love it and it will distinguish you from the competition. (Use this link to take a look…http://spins.spincar.com/poweryachtsinternational/smntf165f516.) 
 2) Make sure that every conversation, every advertisement, every sign in your stores leads with payment and never with the price. Payment plants the Finance message. It also helps to answer the question, “Can I afford this?” Think about the car folks – you’ll never see an ad that says “Get your new Nissan for only $21,000.00”, all you see is “Low payments of $199.00 per month.” Be a payment store and your F&I will benefit. 
 3) Sales sells the units and tees up conversations about extended warranties and other protective products. Sales never formally presents the products and certainly NEVER talks about cost or payment. Make sure that brochures and props regarding these products are highly visible in and around all the units on display. Ensure that when the customers ask your sales team about these products they know this answer, “Gosh, I’m not an expert on those products. Our Delivery Coordinator will go over all of that with you." 
 4) 100% Turnover to Finance must be the rule in your store. Every customer needs to see the Delivery Coordinator. No checks or cash on the sales floor. Yes, even cash buyers see the Delivery Coordinator. Some Cash buyers will convert to finance. All buyers, whether cash or finance MUST get a complete presentation of the Optional Protective Products. This is not just a finance revenue increasing trick – although ensuring 100% turnover will increase revenue. Your place your store in legal jeopardy if you do not present your cash buyers with the same protective options as your finance buyers. Increase revenue and protect yourself with 100% turnover. 
 One other tip to help this process. As soon as your salesperson has met the customer, they should introduce that customer to the Delivery Coordinator with the message, "Once we have decided which unit is right for you, you will be Bob (or Betty) again to go over details." 
 5) Train your Delivery Coordinator to be "aggressive, but graceful in retreat.” You will rarely get more than what you asked for the first time. It is much easier to have a conversation that starts with, “Your monthly payment will only be $299.00 per month and that includes your 8 year engine warranty, interior/exterior protection and GAP Waiver” and then back-walk from there than it is to have a conversation that goes, “You monthly payment for the base unit is $249.00 per month, no we can add an 8 year warranty, interior/exterior protection and GAP for just an additional $50.00 per month.” Start with what is best for you and the customer and walk it back as needed. 


image

 Also, remember and train your Delivery Coordinator in the “Hippocratic Oath of F&I – First, do no harm.” Selling a unit is the first priority – without that, no one makes any money – that said, there is no reason not to be able to gracefully get that unit sold while starting at the top. 
 6) Make Closing/Delivery easy. Send the customer a checklist ahead of closing that tells them what they need at Delivery. This list includes Driver’s License; Full down-payment; insurance binder with the lienholder information; any unique requirements at your store. Include the Optional Protective Product Disclosure (“Sign To Decline” showing what protective products the customer has accepted and what they have declined) in the package of documents that they sign at closing – and make sure that it gets signed. 


image

 7) Finally, survey your customers. Email all of them after the transaction is complete. Understand what is working and what is not working from the customer point of view. Remember, your customer service goal is continual improvement. How do you know what they are thinking if you don’t ask. If you rigorously train in and manage these seven tips, your F&I profits will thank you!

Dealer Profit Services, LLC can help. Whether you want someone to take over your F&I and just drive profit to your store, help you some of the time, need some quick advice or just provide F&I Training/Consulting, we are here to help you. Contact us anytime at info@dealerprofit.com or give us a call at (470) 326-0966. 

Sunday, July 7, 2019

F&I Profits and Benchmarks – Is Your Store Under-Performing?


By Myril Shaw, Dealer Profit Services
F&I should be a very consequential profit center for your store. Here are some benchmarks you can use to tell if you are underperforming – and some tips if it seems like you are.
Key Benchmarks:
  • Over 50% of your deals are financed in-house
  • For financed deals, your average funding/dealer reserve is 4.75% or more of the amount financed
  • Backend products should be sold on 45% – 65% of all financed deals and should add on average about 50% profit on those deals; across all financed deals, backend sales should add an additional 24% – 28% or more profit based on total dealer reserves
Underperforming?
If your store is not seeing these results, it would be easy to blame your Finance Manager… and you might be right, but often there is a much more insidious, and potentially more difficult to correct cause. F&I success starts before the customer ever arrives at your store and the ultimate outcome is often determined before the finance manager ever has a chance to meet the customer. 
Does your website advertise in-house financing? 
You don’t want to give the customer a reason to start shopping financing. Make it clear that you have multiple financing options available. Give your customers a chance to get pre-approved right on your site. (Dealers properly using Soft-Pull pre-approval tools, which have no impact on the customer’s credit score, are seeing an incremental 15% – 20% financed sales per year.) 
Once the customer arrives at your store, does your store environment encourage the right mindset for F&I? Are your salespeople trained to prepare that customer for the F&I conversations that are to come? 
If you have signs advertising low rates, you have already mitigated your ability to maximize F&I success. If you feel compelled to display rates at all, and we would recommend that you advertise payments rather than rates, make sure that rates you advertise allow you to get at least 6% dealer reserve on prime consumers (in today’s environment, that is between 6.24% and 6.9% – the good news is that there do not appear to be more rate increase coming this year – and make sure that “on qualifying credit” is very visible. 
Does your sales team truly sell your products? 
In general, territories are reasonably protected by the franchise. If your salesperson has really caused the customer to fall in love with your product, your prospects of F&I success go way up. Getting this product elsewhere will be inconvenient, at best. The customer can’t just go next door and get the same thing at a different price or rate. Your salespeople need to be stressing the convenience of being able to get the product, service financing and all the optional products and services they may need at your location. Sell the value of ease – train your sales team that all of this is a lifestyle purchase and that everything, the unit the backend products, the Pro Shop items are all there just to ensure a better lifestyle purchase. The sales team should introduce the value of extended service agreements and other backend products, but should not give pricing. They will also make it clear that the customer can get their financing done at your store. When the ugly question comes up, “Can I get 3.9% on this…I saw that advertised down the street?”, the general framework of the answer should be, “Gee, that is something I just don’t have the answer to, but our Delivery Coordinators will be able to work with you on that once we have found exactly the piece of inventory you want. What kind of payment were you looking for? I can let our coordinator know.”Until credit has been run, debt to income established and the overall credit profile reviewed, there is no good reason to make promises or establish expectations. Doing so just stands in the way of F&I success and makes your finance manager’s job nearly impossible. Only after you have established the pre-F&I processes and procedures that maximize the probability of success are you able to judge your F&I department against the success benchmarks. You maximize your F&I profits when you treat F&I as a full sales life cycle process and not just a single point, isolated profit center event. 

Dealer Profit Services, LLC can help. Whether you want someone to take over your F&I and just drive profit to your store, help you some of the time, need some quick advice or just provide F&I Training/Consulting, we are here to help you. Contact us anytime at info@dealerprofit.com or give us a call at (470) 326-0966. 

Sunday, June 23, 2019

Profit Through Protection – Doing It Right


By Myril Shaw, Dealer Profit Services
Are you offering all of your customers all the Optional Protective Products you can?
If the answer is yes, congratulations…you are one of a pretty small club.  If the answer is no, you are probably leaving money on the table.
Going back to the “Yes” answer, are you making sure that your customers know that they have been offered everything – if the answer there is “no”, you could still be at risk.
Let’s start at the beginning.  What are Optional Protective Products?
Your unit comes with certain warranties and other protections direct from the manufacturer.  These can include engine warranties for a specified term, accessory warranties, “stem-to-stern” or “full vehicle” coverages.
Notwithstanding the manufacturer’s products, there is a lot of room to give your customer’s even greater peace-of-mind.  These “Optional Protective Product” offerings may include things such as:
• Pre-paid maintenance (great for customer retention)
• Engine warranties with terms or coverages which exceed those of the manufacturer (note that these are typically transferable and so enhance the value of the unit on resale)
• Accessory warranties with terms or coverages which exceed those of the manufactured and/or on non-manufacturer installed options
• Interior and exterior protection products to ensure that your customer’s unit remains looking like it did the day they purchased it
• Tire and Road Hazard protection which make sure that your customer is not stuck on the side of the road
• GAP Waiver to protect the customer against out of pocket loss payments in the event that their unit is totalled
• And more…
In some quarters, there is a reluctance to offer these products.  Some believe that they are “rip-offs”, others believe that they are just too much trouble.  They are neither.  Your customers are buying a lifestyle and all of these products are designed to protect and enhance that lifestyle – and they do – in every case.
Once you start doing this, you do incur certain responsibilities, and, yes, liabilities.  You MUST guarantee that every customer you sell to gets to hear about every (relevant) Optional Protective Product every time (clearly, cash buyers don’t get offered GAP and people buying a boat with a Mercury engine don’t get offered a Yamaha warranty).  Cash buyers must be offered all the relevant products.  Finance buyers must be offered everything – despite the fact that the amount of these products that can be financed may be limited (in which case, they could be added to the down payment.)
Failure to offer everything to everyone could result in significant consequences.  Customers who were not offered available products and who subsequently needed them may hold you, the dealer, liable…and they will be right, every time.
There is straight-forward protection for you.  It is called the “Sign To Decline” or the “Optional Protective Products Disclosure”.  During Closing/Delivery, the customer signs a document stating that they have been offered and that they have chosen to decline whichever products they declined.
Two things can happen when the customer is presented with this document.  They can sign, and you are protected, or they can ask questions – now you have another chance to sell more.  It doesn’t get better than that.
Make more money and sleep better at night – how good does that sound!
Dealer Profit Services, LLC can help. Whether you want someone to take over your F&I and just drive profit to your store, help you some of the time, need some quick advice or just provide F&I Training/Consulting, we are here to help you. Contact us anytime at info@dealerprofit.com or give us a call at (470) 326-0966. 

Sunday, June 9, 2019

Get Down With The Down!


By Myril Shaw, Dealer Profit Services


"Can I get $0 down?"

How often do you hear that?

Here is the issue!

The natural instinct for every salesperson and for almost every finance person is to say, "Well, we'll see what we can do!"

While that may seem right…it is a horrible answer for the deal.

Of course, you need to be respectful to the customer.  You also have to be respectful of your store, your business and your job.

While the Hypocratic Oath of selling is, "First Do No Harm," the oath of the position is, "Lock It In and Maximize."

A large down-payment does so much for a deal…and a zero-down rarely does anything good.

When you say, in response to, "Can we get $0 down?", "We can look at that – although typically our lenders our looking for 20% down – this is a luxury purchase which is not like a Ford, so the requirements are different.  What can you put down?", this is game changing response.

What does a large down payment do for a deal?  Let's count the ways:

1)    A large down payment indicates commitment to the deal – you know that these people want to make the purchase and that they are financially prepared to;
2)    A large down payment decreases the Loan-to-Value is a very positive way and ensures that the terms on the balance will be as favorable as possible;
3)    A large down payment increase the amount available for backend sales in two ways: first, it simply opens up cash for backend sales; second, it indicates that you can have a conversation about increasing the down payment to include more backend that is effectively paid for with cash – or to reducing their large down payment and including more backend.

Offering $0 Down may be good for the car guys, and it may be polite for the rest of us…it is horrible business for the rest of us.

Reach for 20% down all the time, settle for 10% and politely grumble about less.  It reality, the customers' credit profile, or the price of the unit they are buying, may drive some of this in any case – the moral here is that when it comes to down payments, bigger is better!

I'm down with the down!
Sound familiar?  Let me know at myril@dealerprofit.com.
Make it a practice to do quarterly training with both Sales and F&I on best practices, and make sure to include these Top 10 warnings.
You maximize your F&I profits when you treat F&I as a full sales lifecycle process and not just a single point, isolated profit center event.
Dealer Profit Services, LLC can help.  Whether you want someone to take over your F&I and just drive profit to your store, help you some of the time, need some quick advice or just provide F&I Training/Consulting, we are here to help you.  Contact us anytime at info@dealerprofit.com or give us a call at (470) 326-0966.